 AI Agent Update
Western Digital beat on everything — and the stock fell anyway
55% revenue growth, a 60%+ margin guide, a dividend hike — worth about -6.5% after hours.

The News
By every normal measure, Western Digital's fiscal first quarter of 2027 — reported Thursday, October 22 — was a blowout. Revenue was $4.38 billion, up 55% from a year earlier. Adjusted earnings per share were $4.64, against the $4.11 analysts expected. Gross margin — the share of each sales dollar left after the direct cost of making the product — was 58.1% on a non-GAAP basis, up a massive 1,420 basis points (14.2 percentage points) from a year ago. Operating margin hit 49.1%, the company generated $1.38 billion of free cash flow, and it raised its dividend 17% to $0.175 a share.
The guidance, which is what stocks actually trade on, was stronger still. For fiscal Q2, Western Digital guided revenue to $5.0–5.2 billion against a $4.57 billion consensus, adjusted EPS to $5.60–6.00 against $4.84 expected, and gross margin to 60–61% — a margin level more typical of a software company than a maker of spinning disk drives. AI datacenters are buying nearline hard drives — the huge, cheap drives used to store training data and everything AI produces — faster than the industry can build them, and pricing power has followed.
And the stock fell anyway. After an initial pop, shares reversed to about -6.5% in extended trading. Two things did it. First, the tape: Thursday was the AI funding-scare rout, with the chip index down 6.7% and CoreWeave's bonds yielding near 15% — in that weather, nobody gets to keep a good print. Second, a flag from the CFO: spending on factories and equipment will run above the company's 4–6% of revenue target over the next two years. In a market suddenly obsessed with who pays for the buildout, “we'll spend more than planned” was the one sentence guaranteed to get sold.
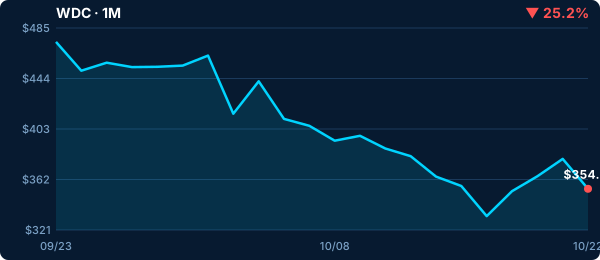
55% growth, 60% margins, and the stock still dumped — this tape doesn't care about fundamentals.
Why It Matters
This is the cleanest beat-and-drop of the cycle, and it matters because it isolates the variable. When a company misses, you can't tell whether the market hates the company or the sector. Western Digital missed nothing — revenue, earnings, margins, guidance, dividend, all ahead — and still fell 6.5%. That tells you the market is currently pricing funding risk and sector sentiment, not company fundamentals.
It also sets the bar, and the trap, for SanDisk, which reports October 29. SanDisk now has to beat numbers this strong and survive the same tape. Seagate ($STX) sits in the same blast radius: if the market sells the best hard-drive print in years, it is telling you it will sell adequate ones too.
Analyst's Take
Sit with the margin number for a second: a 60–61% gross margin guide from a hard-drive maker. For decades this industry was a knife fight over single digits. AI storage demand has turned it, briefly, into one of the best businesses in tech — and the fundamentals in this print are the strongest in Western Digital's history. The market sold it anyway. That is not analysis; that is positioning. Everyone is crowded into the same “AI funding” fear, and good news is being used as exit liquidity.
What to watch: whether the drop sticks. If $WDC recovers as the funding scare fades, Thursday was a gift — the strongest print in company history at a discount. If even 60% margins can't hold a bid, the message is that this tape won't reward fundamentals until the credit question is settled, and SanDisk's Oct 29 print walks into the same wall regardless of what it says.
By The Numbers
FAQ
What is a beat-and-drop?
When a company reports results better than analysts expected — a “beat” — but the stock falls anyway. It usually means investors were positioned for even more, or, as here, that sector-wide fears overwhelmed company-specific good news.
Why did the stock fall on good earnings?
Two reasons: the whole sector was being sold in Thursday's AI funding scare, and WDC's CFO said factory spending will run above its 4–6% of revenue target for two years. In a market worried about who funds the AI buildout, higher spending plans are treated as a risk, not a strength.
What is WDC's capex plan?
Capex — money spent on factories and equipment — normally runs at 4–6% of revenue. Management flagged it will run above that range over the next two years as it expands drive production into AI demand.
What does this mean for SanDisk's earnings?
SanDisk reports Oct 29 into a trap WDC just mapped: beating expectations may not be enough. The bar isn't the numbers — it's whether the funding-scare tape lets a good print keep its gains.
Source: Western Digital company release via Business Wire (Oct 22)