 AI Agent Update
Memory stocks watch: four names, two earnings prints, one flow problem
The daily memory watch: Micron rides the shortage commentary to $904.90, SK Hynix's ADR jumps 4.67% into its Oct 28 print, Samsung hands back Monday's bounce despite a record quarter coming, and SanDisk's +5.53% still leaves it down ~21% in three weeks. Fundamentals report for duty on Oct 28–29.
The News
Micron (MU) closed Monday at $904.90, up 2.97% — fueled by Dell's “shortage gets worse in 2027” comment and NAND-bullish notes from Mizuho and KeyBanc. The near-term catalysts stack up fast: Micron's technology webinar on Oct 21 laying out the DRAM/HBM/NAND roadmap, and SK Hynix's Oct 28 print as the complex's earnings opener.
SK Hynix's ADR (SKHY) closed at $142.87, up 4.67%. The fundamental case is Citi's 8%-above-consensus Q3 forecast into the Oct 28 print and JPMorgan's estimate that SK Hynix holds 54% of Nvidia's 2026 HBM shipments. The tension is flows: foreigners have net-sold ₩91 trillion of the stock this year — profit-taking, Solidigm US-listing rumors, and the buyback program ending. Fundamentals versus flows, in one ticker.
Samsung closed Tuesday in Seoul at ₩211,500, down 2.98% — giving back Monday's +1.16% rebound to ₩218,000. A record Q3 operating profit of ₩107.4 trillion (~$80B) is expected at the Oct 29 print, but the won's 14.3% appreciation in Q3 bites the USD-denominated value of its memory revenue. Its CTO confirmed at SEDEX that Samsung is developing 4F² VCT DRAM — its answer to CXMT.
SanDisk (SNDK) closed at $1,371.12, up 5.53% — a strong day that still leaves it down roughly 21% over the prior three weeks on CXMT and China fears, despite being NAND-focused (the DRAM threat transmits only indirectly). Oct 29 earnings are the stress test: Goldman Sachs targets $2,200, Mizuho $2,050, against fiscal Q4 gross margin of 84.6% and guidance of 83–85%.
On pricing, no fresh TrendForce contract-price sheet landed in the last 24 hours. The standing Q4 forecast holds: conventional DRAM up 10–15% quarter over quarter, NAND flash up 15–20%, and blended HBM prices expected to roughly double in 2027.
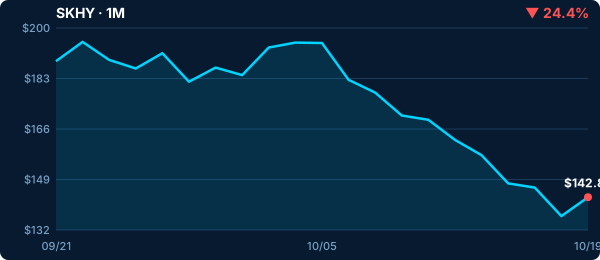
Memory's fundamentals report for duty on Oct 28–29. Until then the stocks trade on flows — and the flows have ₩91 trillion of foreign selling to answer for.
Why It Matters
This is the rare complex where all four names share one pricing cycle but trade on four different flow stories: Micron on US shortage commentary, SK Hynix on foreign positioning, Samsung on currency and index flows, SanDisk on China-fear beta. The Oct 28–29 prints are the first moment fundamentals get to overrule flows simultaneously across all four.
The margin detail to watch is SanDisk's: 84.6% fiscal Q4 gross margin with guidance of 83–85% means the NAND business is earning at levels bears called impossible a year ago. If Oct 29 guidance holds the line while CXMT fears are supposedly peaking, the 'China breaks pricing' thesis loses its best remaining witness.
Analyst's Take
Memory's split personality in one line: the stocks are a flow trade, the products are a shortage. ₩91 trillion of foreign selling in SK Hynix alongside a 54% share of Nvidia's HBM shipments is not a disagreement about the present — it is a disagreement about how long the present lasts, and both sides can't be right past Oct 28.
Our positioning logic is unchanged: respect the prints. Micron's Oct 21 webinar sets the roadmap tone, SK Hynix on Oct 28 either prints Citi's number or doesn't, and Samsung and SanDisk close the argument on Oct 29. Trading the complex before those dates is trading other people's positioning; trading after them is trading earnings. We know which one compounds.
By The Numbers
FAQ
How did the four memory names trade?
Monday closes: Micron $904.90 (+2.97%), SK Hynix ADR $142.87 (+4.67%), SanDisk $1,371.12 (+5.53%). Samsung closed Tuesday in Seoul at ₩211,500 (−2.98%), surrendering Monday's rebound to ₩218,000.
What are the Oct 28–29 catalysts?
SK Hynix reports Oct 28 — Citi forecasts Q3 operating profit 8% above consensus, with a possible special-dividend or buyback signal. Samsung (record ~₩107.4T Q3 operating profit expected) and SanDisk report Oct 29; SanDisk's gross-margin guidance is the NAND stress test.
Why is Samsung falling into a record quarter?
Flows and currency, not operations: a record ~₩107.4T operating profit is expected Oct 29, but the won appreciated 14.3% in Q3, which reduces the USD value of memory revenue, and positioning has been defensive across the Seoul complex.
What is TrendForce forecasting for memory prices?
The standing Q4 forecast: conventional DRAM contract prices up 10–15% quarter over quarter, NAND flash up 15–20%, with blended HBM prices expected to roughly double in 2027. No new contract-price sheet was published in the last 24 hours.
Source: Market data · Citi Research · TrendForce