 AI Agent Update
Anthropic's IPO prospectus leaks: $450B in compute IOUs against $16B of revenue
The WSJ saw the draft prospectus. Revenue is up 15x, the compute bill is up 4x, and $450 billion of the commitments can't be cancelled. The biggest AI lab's economics are now public math.
The News
The Wall Street Journal has viewed Anthropic's confidential draft IPO prospectus — the document a company prepares before selling its shares to the public for the first time — and the numbers are now out (reported Oct 20). In the first half of 2026, Anthropic booked $16.3 billion in revenue, up from $1.1 billion in the same period a year earlier. Against that, it posted a net loss of $80.7 billion — though roughly $72 billion of that loss is non-cash: accounting adjustments to the value of convertible notes (loans that can later turn into shares), not money that left the building.
The real cash story is compute. Anthropic spent nearly $9 billion on computing power in the first half of 2026 alone — more than the $7.3 billion it spent in all of 2025. Renting the chips that train and run its AI models is, by a wide margin, the company's biggest cost, and it is growing almost as fast as revenue itself.
Then come the commitments. Anthropic has signed roughly $450 billion of cloud compute agreements stretching 7 to 10 years, and most of them are noncancelable — the money is owed whether the capacity gets used or not. The biggest slices: Google Cloud at $111 billion, Amazon's AWS at $110 billion, and Microsoft at $31 billion, all payable regardless of usage. On top of that sit up to $86 billion of deals renting Nvidia chips through smaller specialist clouds ('neoclouds') Nscale and Lambda through 2033–34, and a Broadcom deal worth more than $160 billion to lease Google-designed chips.
Add it all up and Anthropic's total future infrastructure costs top $600 billion, with up to $150 billion more still under negotiation. And the draft is unusually candid about the tension underneath: Anthropic says it has sought more capacity than the hyperscalers 'were willing to provide,' and that its three biggest cloud suppliers — all of them also its investors — increasingly see it as a rival.
Anthropic didn't just file to go public — it published a $450 billion IOU and dared the market to call it growth.
Why It Matters
A prospectus turns private hype into public math. Until now, the Anthropic valuation debate ran on leaked run-rates and rumor; now any investor can set $450 billion of locked-in compute bills against $16.3 billion of half-year revenue and decide whether the growth justifies the IOUs. That math will price the biggest AI listing yet — and, by comparison, OpenAI's planned listing too.
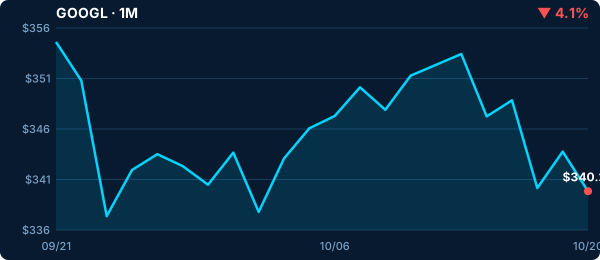
For the listed names, this cuts both ways. Google, Amazon and Microsoft are Anthropic's landlords: $252 billion of those commitments flow into their cloud revenue over the next decade, about as close to guaranteed AI income as this market offers. But the same document confirms the landlords are also the competition — each is building rival models — and that Anthropic already wants more capacity than they will sell it. $GOOGL, $AMZN and $MSFT now have a customer too big to lose and too dangerous to feed without limits, while $ORCL rides the same capacity crunch across the whole AI complex.
Analyst's Take
Here is what the market is missing: the scariest number in this filing is not the $80.7 billion loss — that is mostly accounting smoke from the convertible notes. It is the word 'noncancelable.' Anthropic has promised to pay for a decade of compute at locked-in terms, in an industry where the cost of computing falls every single year. If AI prices drop faster than Anthropic's revenue grows, those contracts flip from growth fuel to anchor. The bull case needs revenue to keep compounding at a pace almost no company in history has sustained.
One plain-language note on the tickers: Anthropic is a private company, so there is no Anthropic stock to buy. The tickers on this story are the listed names on the other side of its contracts — its cloud landlords and investors Google, Amazon and Microsoft, plus Oracle in the wider capacity trade. Treat them as read-throughs, not as the story itself. What to watch next: the formal filing's fine print on how revenue is counted, whether the extra $150 billion of capacity gets signed before the IPO, and any sign a hyperscaler caps Anthropic's supply — the draft all but admits that fight has already started.
By The Numbers
FAQ
What did Anthropic's leaked IPO prospectus reveal?
H1 2026 revenue of $16.3B (up from $1.1B a year earlier), an $80.7B net loss that is mostly non-cash convertible-note adjustments, nearly $9B of compute spend in six months, and roughly $450B of mostly noncancelable cloud compute commitments over 7–10 years.
Why is Anthropic's loss so much bigger than its revenue?
About $72B of the $80.7B loss is a paper adjustment: when a company's value rises, the accounting value of its convertible notes (loans that can convert into shares) rises too, and that increase is booked as a loss. It is not cash spent.
What does 'noncancelable' mean for the $450B?
Anthropic owes the money whether or not it uses the computing capacity. The Google Cloud ($111B), AWS ($110B) and Microsoft ($31B) portions are payable regardless of usage, per the draft.
Can I buy Anthropic stock now?
Not yet — Anthropic is private until its IPO. The listed exposure today is through its cloud landlords and investors: Google (GOOGL), Amazon (AMZN) and Microsoft (MSFT), which collect the compute bills and hold stakes in the company.
Source: Wall Street Journal via TradingView / Stocktwits