
MasTec buys Murphy for $1.25B to capture datacenter cooling work; shares fall 10%+
MasTec has paid $1.25 billion in cash for mechanical contractor Murphy Corp, borrowing the full amount on a term loan — and the market read the deal as a leverage event, sending MasTec shares down more than 10% on Friday.
The News
MasTec, Inc. announced on Friday, November 20, that it has completed its acquisition of Murphy Corporation, one of the largest mechanical contractors in the US, for approximately $1.25 billion in cash, subject to customary purchase price adjustments plus a potential earnout tied to Murphy's cumulative financial performance over the three years after closing. An earnout is extra payment that depends on the acquired business hitting financial targets after the deal closes.
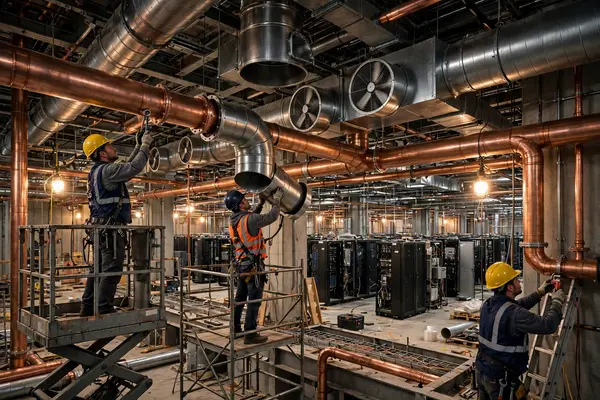
Murphy is a St. Louis-based, family-owned mechanical, plumbing, HVAC, refrigeration and process-infrastructure contractor founded in 1907. It becomes a new operating group inside MasTec, reported in its Clean Energy and Infrastructure segment, with its management team staying in place. MasTec says the deal expands its presence in datacenters, defense, healthcare and advanced manufacturing, adding the specialised fabrication, engineering and mechanical-cooling capabilities hyperscalers need as datacenters move from construction into continuous operation.
MasTec arranged a bank term loan to finance the deal, and its SEC filing shows it borrowed the full $1,250 million term loan on November 20 to fund the acquisition. The loan is a 364-day term facility maturing November 19, 2027, with no amortization — a one-year bridge that must be refinanced. Its September 30 pro forma net leverage is estimated at 2.7x, with deleveraging below 2.0x expected during 2027. Leverage here means debt compared with earnings — 2.7x means the company's net debt is about 2.7 times its annual earnings before interest, tax, depreciation and amortisation. MasTec said substantially all closing conditions have been satisfied and it expects to close expeditiously, though its own release states no closing date.
MasTec bought the cooling capacity the AI buildout needs — and borrowed every dollar of the price to do it.
Why It Matters
This matters because cooling is becoming one of the binding constraints on the datacenter buildout. As AI servers get more powerful they generate more heat, and the specialised mechanical work — the cooling systems, fabrication and plumbing that keep a datacenter running around the clock — is a skill in short supply. Buying Murphy gives MasTec that capability in-house, at a moment when hyperscalers are shifting from building datacenters to operating them continuously.
Murphy's numbers explain the strategic appeal. About $775 million in projected 2026 revenue and about $140 million in adjusted EBITDA — earnings before interest, tax, depreciation and amortisation, a rough measure of operating profit — after double-digit revenue and EBITDA growth over the two years ended March 31, 2026, is a substantial, growing business in exactly the market MasTec wants to serve. The price, about $1.25 billion, is roughly nine times that projected EBITDA, which is a full but not extraordinary price for a growing specialist contractor.
The market, however, read the deal as a leverage event rather than a growth story. MasTec shares fell more than 10% in regular trading on Friday, the day of the announcement. Borrowing the full purchase price in one go lifts the company's debt load, and investors punished the stock even though MasTec says it expects to bring leverage below 2.0x during 2027. No verified MasTec closing share price is available in the research for this story, so none is cited here.
Analyst's Take
Our call is Mixed. The industrial logic is sound: datacenter cooling is scarce, valuable capacity, and Murphy is a growing business that fits it. But the financing is the other half of the story — a fully debt-funded $1.25 billion deal that lifts leverage to 2.7x — and Friday's 10%+ share drop is consistent with the market weighing the debt more heavily than the strategy, though the drop came on a day the whole AI complex sold off (Nasdaq −5.28%), so the deal alone is not established as the cause.
What to watch next is the integration and the refinancing path. The deal closed on November 20 and MasTec has already drawn the loan — a 364-day term loan maturing November 19, 2027, which must be refinanced within a year. The test will be whether Murphy's earnings arrive as projected and pull leverage below 2.0x during 2027 as promised, and whether the earnout — extra payment tied to three years of performance — ends up costing more or less than expected.
For investors, this is a deal to judge on execution rather than announcement. If Murphy delivers its $775 million revenue and $140 million EBITDA and MasTec pays down the loan on schedule, the cooling capacity will look well bought. If the debt lingers or the integration stalls, Friday's verdict will look prescient. Reader poll: Was MasTec right to borrow $1.25B for Murphy? Vote: Yes, cooling is key, No, too much debt, Too early to tell.
Are you bullish or bearish on this story?
By The Numbers
FAQ
What is HVAC?
HVAC stands for heating, ventilation and air conditioning. In a datacenter it means the systems that keep powerful AI servers cool enough to run safely around the clock.
What is adjusted EBITDA?
EBITDA is earnings before interest, tax, depreciation and amortisation — a rough measure of a company's operating profit. Adjusted EBITDA strips out one-off items to show the underlying business more clearly.
What is leverage?
Leverage is how much debt a company carries compared with its earnings. At 2.7x net leverage, MasTec's net debt is about 2.7 times its annual earnings on that measure — higher leverage means more debt to service.
What is an earnout?
An earnout is extra money the buyer pays later if the acquired business hits agreed financial targets after the deal closes. It shares the risk between buyer and seller.
👁
Source: BusinessWire